By Aidan Nicholls September 27, 2026
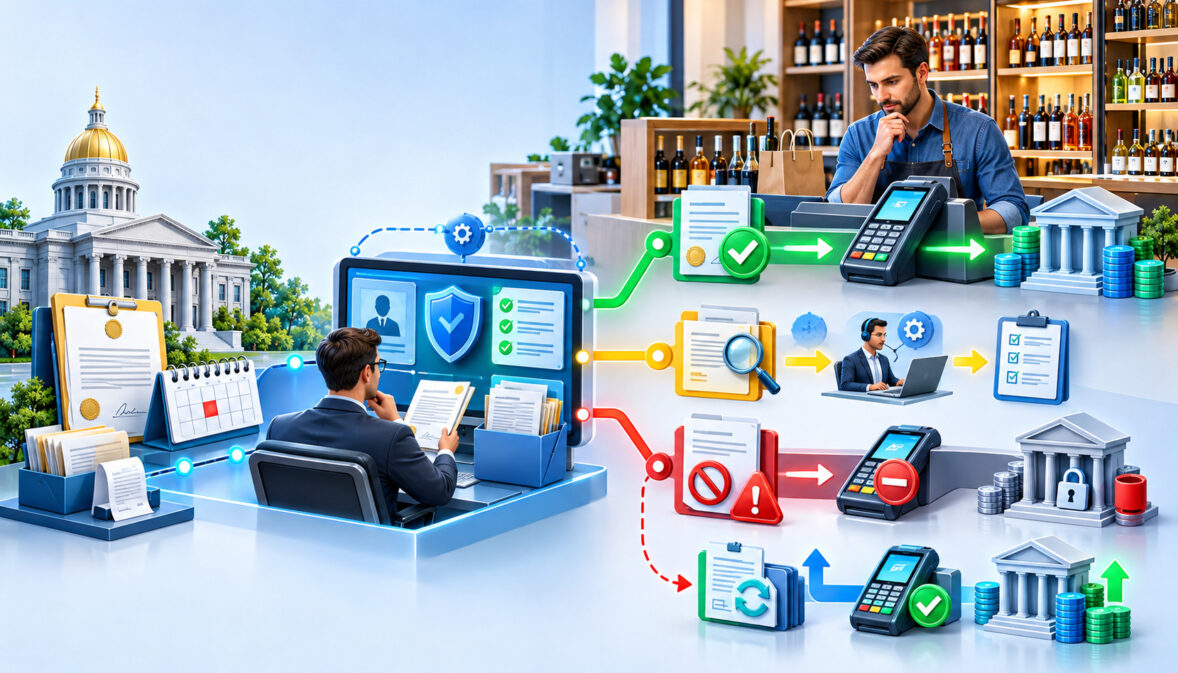
A liquor license lapse merchant account problem can trigger a processor compliance review because the account was underwritten for a licensed alcohol business. The response is not universally automatic: the processor may request updated licensing, restrict processing or funding, or terminate under its agreement. Merchants must stop prohibited alcohol sales and promptly document the licensing situation.
| License Status | Can Alcohol Sales Continue? | Likely Processor Concern | Merchant’s Immediate Action |
| Active, renewal pending | Depends on whether existing legal authority remains effective under the jurisdiction’s rules | Proof of renewal and continuing authority | File early and retain official confirmation |
| Administrative lapse/expiration | State- and license-specific | Licensing condition may no longer be verified | Confirm legal authority before selling alcohol and contact processor |
| Suspension | Controlled by the order, effective dates, applicable law, and any actual stay | Regulatory, compliance, and approved-business-model risk | Follow the order and notify processor where required |
| Revocation | Generally no continued privileges under the revoked license; exact procedures vary | Continued eligibility for alcohol-business underwriting | Stop prohibited activity and contact processor |
| Reinstated/renewed | Authority restored subject to the regulator’s effective date and conditions | Documentation and underwriting refresh | Send proof and request review of account restrictions |
A liquor license lapse merchant account issue becomes easier to manage when four separate concepts are kept apart. The state or local alcohol regulator determines whether alcohol may lawfully be sold, while the merchant agreement controls the contractual card-acceptance relationship.
The processor or acquiring bank separately makes its own underwriting and risk decisions. The merchant category and approved business model describe what the account was established to process.
None of those substitutes for another.
Why an Active Liquor License Matters to Your Merchant Account
A liquor store merchant account is normally underwritten around a regulated business model. An active alcohol license may therefore be important evidence that the merchant remains legally authorized to conduct the principal activity disclosed when the account was approved.
During alcohol merchant underwriting, the processor or acquiring bank may examine the legal entity, owners, premises, anticipated sales, transaction channels, website, bank account, business licenses, alcohol license, and merchandise being sold. Requirements vary by provider, and an underwriting refresh may request some or all of the same information again later.
Because alcohol sales involve regulatory and underwriting considerations that ordinary retail accounts may not face, the merchant’s alcohol retail merchant-account profile should accurately reflect the products, locations, and sales channels being processed. Processor approval, however, does not make an otherwise prohibited alcohol transaction lawful.
How ABC License Verification Works During Underwriting
ABC license verification underwriting is the process of comparing the merchant’s claimed alcohol business with licensing, ownership, location, and identity records. During initial approval or a later merchant underwriting review, the provider may confirm that the legal entity, DBA, licensed premises, ownership, and license status still match the business being processed.
An underwriter may request:
- current liquor license;
- state entity registration;
- local business license;
- EIN or tax-identification records;
- ownership and beneficial-owner information;
- government identification;
- premises address;
- bank documentation; and
- website or ecommerce information where relevant.
The operating profile should also match the store’s actual checkout environment. If the application describes an attended liquor-store location, the POS configuration should support the store’s real payment and ID-check workflow rather than introducing sales channels or transaction methods that were never disclosed during underwriting.
“ABC” is useful nationwide shorthand, but it is not a universal agency name. Depending on the jurisdiction, alcohol regulation may sit with an Alcoholic Beverage Commission, Liquor Control Commission, State Liquor Authority, Department of Revenue, Alcohol and Tobacco Commission, or another agency.
California, for example, uses the Department of Alcoholic Beverage Control, while New York uses the State Liquor Authority and Pennsylvania uses the Liquor Control Board.
Will the Processor Find Out if the License Expires or Is Suspended?
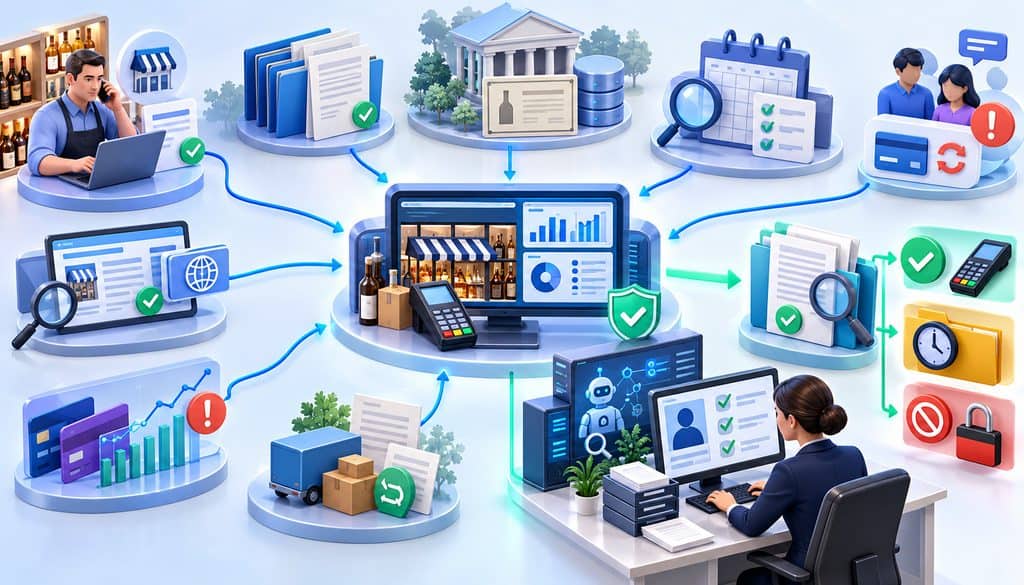
A merchant should not assume that a licensing change will remain invisible. Processors and acquirers can discover license problems through merchant disclosures, public records, document-refresh programs, risk reviews, or other compliance processes.
Possible discovery points include:
- scheduled underwriting refreshes;
- annual or periodic document requests;
- merchant self-reporting requirements;
- publicly searchable license databases;
- complaint or chargeback investigations;
- regulatory or compliance reviews;
- website or business-profile reviews;
- material-change notifications; and
- unusual account activity that prompts a new review.
For example, California ABC maintains publicly searchable information concerning existing, pending, and former licenses.
That does not mean every processor automatically checks every state alcohol database every day. Providers may use manual reviews, automated compliance systems, third-party verification tools, public records, or combinations of these methods. Monitoring practices differ.
The safest operational assumption is therefore not “the processor will never know,” but “the merchant should satisfy any contractual disclosure obligation and be prepared to document its current status.”
A Lapse, Suspension, and Revocation Are Not the Same Event
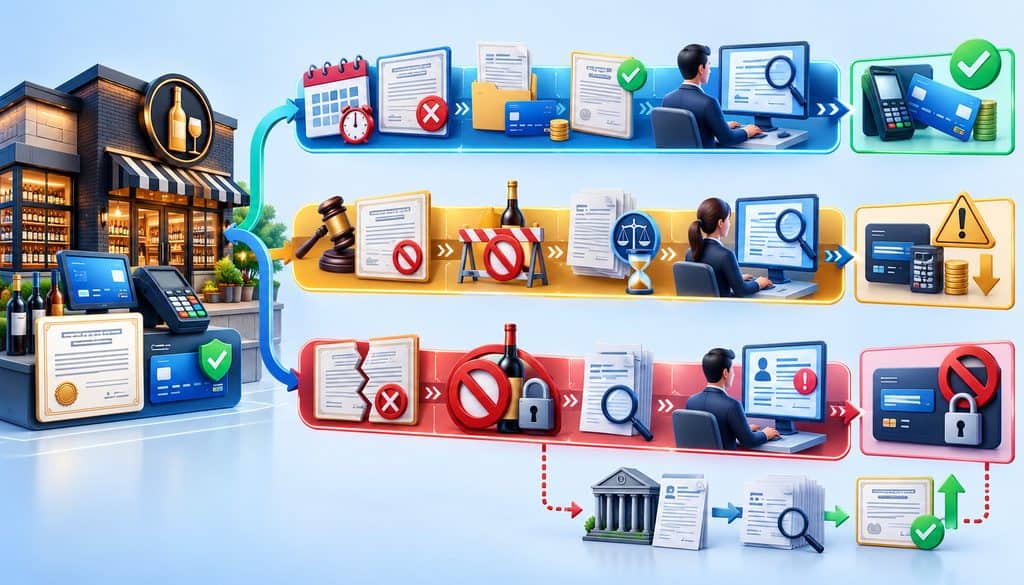
An administrative expiration, disciplinary suspension, and revocation create different regulatory facts and can create different underwriting risks. The terminology and legal consequences are jurisdiction-specific.
An administrative lapse may result from a missed renewal filing, unpaid renewal charge, incomplete application, missing prerequisite, or processing gap. Whether alcohol sales must stop during that gap depends on the jurisdiction’s actual rule.
A suspension normally removes or limits license privileges for a defined period or under specified conditions following regulatory action. Its effect depends on the governing order, effective date, license type, appeal procedure, and whether a legally effective stay has actually been issued.
Revocation is generally more serious because the regulator has terminated the license authority rather than merely interrupting it temporarily. Reapplication and appeal rights vary by jurisdiction.
| Issue | Lapse/Expiration | Suspension | Revocation |
| Licensing status | Credential expired or renewal status unresolved | Privileges restricted for the period/order specified | Licensing authority terminated |
| Typical cause | Missed filing, fee, deficiency, processing issue | Enforcement or disciplinary action | Serious/final licensing action under applicable procedure |
| Ability to sell alcohol | Depends on jurisdiction and any pending-renewal provision | Depends on the suspension order, effective date, and any valid stay | Generally no privileges under the revoked license, subject to applicable procedure |
| Underwriting concern | Can merchant still lawfully conduct the approved business? | Regulatory event plus possible material business change | Fundamental eligibility for the approved alcohol business |
| Documents processor may request | Renewal receipt, status confirmation, current license | Order, dates, appeal/stay documents, business plan during suspension | Revocation order, appeal status, updated business information |
| Possible merchant-account response | Document request, review, restrictions, or other contract-based action | Compliance review, processing/funding restrictions, re-underwriting, or termination depending on contract | Potential suspension or termination and re-underwriting if licensing is later restored |
| Reinstatement path | Complete renewal/reactivation process | Satisfy suspension/reinstatement requirements | Jurisdiction-specific appeal, reapplication, or other authorized procedure |
An appeal should never be described as automatically restoring alcohol-selling privileges. Whether an appeal stays an order is a legal question controlled by the applicable jurisdiction and procedural posture.
What Can Happen to a Merchant Account After a Liquor License Lapse?
A liquor license lapse merchant account problem can trigger a risk or processor compliance review, but there is no universal rule that an expired license automatically freezes funds or closes the account. The response depends on the merchant agreement, acquirer policy, licensing facts, approved business model, and transactions the merchant remains legally allowed to submit.
- request a current license;
- request a written explanation;
- place the account into compliance review;
- restrict particular transactions;
- adjust processing limits;
- delay settlement where contractually permitted;
- review or establish a reserve where the agreement permits it;
- suspend card acceptance;
- request re-underwriting; or
- terminate the merchant relationship.
These outcomes are separate concepts.
A state liquor-license suspension restricts regulatory privileges. A processor account suspension restricts use of the payment account. A funding delay changes settlement timing. A reserve retains funds pursuant to contractual risk terms. Merchant-account termination ends or substantially ends the processing relationship.
One should not be substituted for another.
Current provider agreements illustrate why the merchant’s own contract controls. For example, Stripe’s current service terms expressly describe contractual reserve rights under specified circumstances; that is a Stripe contract provision, not a nationwide merchant-services rule.
Read the Merchant Agreement Before You Assume What Happens
Before predicting what a liquor store account termination or card processing funding hold will look like, retrieve the merchant agreement actually governing the location.
Relevant provisions may appear under:
- legal compliance;
- licenses and permits;
- merchant representations;
- prohibited activity;
- material changes;
- change in business type;
- ongoing underwriting;
- information requests;
- termination;
- reserve rights;
- withholding or delayed settlement; and
- card-network compliance.
A generic payment-industry practice is not the same thing as a contractual right.
Maintain the complete agreement, applicable program guide, amendments, pricing schedule, acquiring-bank terms, and material correspondence. If a clause needs legal interpretation, use qualified counsel rather than relying on a generalized article.
Liquor License Renewal Merchant Services Planning Should Start Early
Liquor license renewal merchant services planning works best when renewal is treated as both a regulatory deadline and an underwriting-document deadline.
For every location, maintain:
- current expiration date;
- earliest permitted renewal date;
- filing deadline;
- confirmation or application number;
- payment receipt;
- inspections or prerequisites;
- responsible employee;
- processor document-update date; and
- an internal escalation date if approval remains unresolved.
For a multi-location retailer, maintain each license separately. California ABC, for example, states that each license number must be renewed separately through its online system.
Workflow 1: Before a Liquor License Expires
- Verify the regulator’s current instructions for the exact license class.
- Confirm the expiration date and first date renewal may be filed.
- Check entity, ownership, address, local-permit, tax, and other prerequisites.
- File as early as the regulator permits when practical.
- Preserve the application, receipt, payment confirmation, and correspondence.
- Track deficiencies until resolved.
- Check whether the processor requires a refreshed license.
- Escalate internally before expiration if regulatory approval remains unresolved.
- Determine the actual legal rule for operations after expiration—do not assume a grace period.
- Save the final renewed credential and schedule the next cycle.
There Is No Single Nationwide Liquor-License Renewal Cycle
Liquor-license periods, filing windows, late-renewal procedures, penalties, pending-renewal rights, and temporary operating authority vary substantially by state and sometimes by local licensing body.
California provides a useful example of why nationwide generalizations fail. California ABC currently states that licenses renew on a 12-month basis and, under its cited statutory framework, describes a specific 60-day period after expiration during which a licensee can legally operate while renewing subject to the prescribed penalty. That is California’s rule, not a nationwide grace period.
Texas has a materially different formulation. TABC states that renewal can be submitted up to 30 days before expiration and up to 30 days afterward with a late fee, but licensed activity must stop after expiration unless a renewal application with fees is pending with TABC.
Representative State Renewal Examples — Verified September 2026
| State | Licensing Authority | Renewal Pattern | Late/Pending Renewal Rule | Merchant Action | Verified |
| California | Department of Alcoholic Beverage Control | Licenses renew on a 12-month basis | ABC describes specific post-expiration renewal/reactivation provisions under California law | Pay before expiration where possible; use current ABC instructions for the license | Sept. 2026 |
| Texas | Texas Alcoholic Beverage Commission | TABC permits renewal beginning up to 30 days before expiration | Up to 30 days late with fee; licensed activity after expiration depends on a pending renewal application with fees | File in AIMS and verify pending status before relying on continued authority | Sept. 2026 |
| Pennsylvania | Pennsylvania Liquor Control Board | Renewal/validation schedules vary by licensing district; many calendar-year licensees follow separate dates | Rules depend on district/license and current PLCB process | Use the PLCB district schedule rather than assuming an anniversary date | Sept. 2026 |
| New York | New York State Liquor Authority | Retailers use the Authority’s current renewal process and applicable renewal forms/advisories | Late-renewal requirements exist for retail licensees; exact consequences and prerequisites should be checked for the applicable license | Follow the current Authority renewal advisory and retailer instructions | Sept. 2026 |
| Florida | Division of Alcoholic Beverages and Tobacco, DBPR | Renewal procedures depend on the applicable license/renewal group | DBPR maintains a delinquent-renewal process for licenses placed into null-and-void status for nonrenewal | Check current DBPR instructions for the applicable license series rather than generalizing | Sept. 2026 |
Official renewal resources worth bookmarking include California ABC licensing and renewal information, Texas TABC renewal guidance, and Pennsylvania PLCB renewal schedules.
The operative lesson is simple: “renewal pending” only helps if the applicable regulator’s rules give that status a particular legal effect.
What Paperwork Should Be Ready Before Renewal?
A reusable file can reduce both regulatory and payment-underwriting friction.
Possible documents include the current license, renewal application, submission confirmation, payment receipt, entity records, ownership information, premises documents, local approvals, tax-clearance material, insurance certificates, leases, and updated contact details.
Not every jurisdiction requires every item.
Expert insight placeholder: Add a verified quote from an alcohol-licensing attorney, former state alcohol regulator, merchant-underwriting professional, or hospitality compliance consultant explaining why merchants should treat license renewal as both a regulatory deadline and an underwriting deadline.
What to Do if the License Has Already Lapsed or Been Suspended
First determine what the regulator says you are legally allowed to do. Then address the processor relationship. Do not reverse that order.
Workflow 2: Lapse or Suspension Response
- Confirm the exact license status using the regulator’s official records or order.
- Determine the effective date and whether alcohol sales must stop.
- Verify whether a pending renewal, appeal, or actual issued stay changes the legal position.
- Preserve the renewal filing, regulatory order, payment receipts, and correspondence.
- Identify transactions that remain legally permissible.
- Review merchant-agreement notification and material-change provisions.
- Contact processor/acquirer compliance where notice is required or prudent.
- Provide the license number, affected location, official status, dates, and supporting documents.
- Ask in writing whether the existing account may process remaining lawful merchandise.
- Preserve communications and settlement records.
- Send renewed or reinstated documentation when issued.
Do not rely on a clerk, salesperson, processor representative, or store employee saying that a license is “basically active.” Regulatory authority should be confirmed from an authoritative source.
Suspended Liquor License Card Processing Requires a Different Response
Suspended liquor license card processing presents a different underwriting question from a late administrative renewal because suspension may reflect a formal regulatory action affecting the approved business model.
The processor may want to know:
- why the license was suspended;
- exact start and end dates;
- whether an appeal has been filed;
- whether a stay has actually been issued;
- whether the location remains open;
- what goods remain legally sellable;
- how much of ordinary volume comes from alcohol;
- whether operations have materially changed; and
- what regulator action is needed for restoration.
Pennsylvania illustrates why the exact enforcement process matters: the PLCB issues and renews licenses, while liquor-law enforcement and citation adjudication involve other state bodies, including the Pennsylvania State Police Bureau of Liquor Control Enforcement and the Office of Administrative Law Judge.
An appeal filing by itself should therefore never be represented to a processor as proof that the suspension has been stayed.
Notify the Processor During a Suspension Appeal—Do Not Wait for a Compliance Review
Where the merchant agreement requires disclosure of a material regulatory change, provide objective facts rather than conclusions.
A useful notification packet identifies:
- merchant ID;
- legal and DBA names;
- affected location;
- license number;
- regulator;
- effective suspension dates;
- appeal/review status;
- documented stay, if one exists;
- remaining legally permissible merchandise;
- next hearing or agency milestone; and
- copies of the official documents.
Proactive notice does not guarantee uninterrupted processing, normal settlement, absence of reserves, or continued approval.
Its purpose is narrower: give the processor accurate information on which to conduct its own merchant underwriting review.
Selling Non-Alcohol Inventory During a Suspension
The fact that alcohol sales are restricted does not by itself answer whether the store may conduct other retail activity or whether its existing MID may be used for that activity. Three independent questions have to be resolved.
A package store may stock mixers, snacks, water, soft drinks, ice, glassware, gifts, and other general merchandise. Tobacco is another regulated category and may involve separate licensing requirements.
1. Is the non-alcohol activity lawful?
Read the suspension order and applicable state/local rules. The answer cannot be assumed nationwide.
2. Does the merchant agreement permit continued processing?
The processor or acquirer separately decides whether the merchant relationship remains acceptable.
3. Is the underwriting profile still accurate?
If the store materially changes from predominantly alcohol retail to another business model, the processor may want updated information or re-underwriting.
If alcohol sales later resume, the checkout workflow should still keep age verification and payment authorization as separate compliance controls, because successful card authorization does not establish that an alcohol sale is legally permissible.
MCC 5921 Does Not Give Permission to Sell Alcohol
Mastercard’s February 2026 merchant reference documentation identifies MCC 5921 as “Package Stores, Beer, Wine, and Liquor” and describes merchants selling packaged alcoholic beverages for off-premises consumption.
That is a payment-network classification. It is not a liquor license.
An MCC does not override a suspension, extend an expired license, or grant permission to sell a regulated product. MCC assignment is part of acquiring and transaction classification, and merchants should not intentionally seek a false category to conceal the actual business.
See the current Mastercard merchant MCC reference and Visa’s official rules and Merchant Data Standards resources for network-level classification materials.
Do Not Run Alcohol Sales Through Another Merchant Account
A suspension is not a reason to route prohibited or misrepresented transactions through:
- another store’s MID;
- another legal entity’s merchant account;
- an unrelated ecommerce account;
- a restaurant merchant account;
- a general-retail account; or
- someone else’s terminal.
Doing so can create inaccurate merchant identification, incorrect underwriting information, business-model mismatches, merchant-agreement violations, and possible card-network compliance problems.
If alcohol sales are prohibited, they should stop for the period required by law or order. Payment routing cannot cure a licensing restriction.
Rebuilding the Merchant Account After License Reinstatement
Regulatory reinstatement restores whatever authority the regulator’s order or license provides, but it does not necessarily update the processor’s records or reverse processor-imposed restrictions automatically.
Workflow 3: Reinstatement Packet
- Obtain the renewed or reinstated license.
- Save the regulator’s reinstatement order where applicable.
- Confirm the effective date.
- Include proof that required conditions were completed where relevant.
- Add current business/entity records if anything changed.
- Add current ownership and bank documentation if requested.
- Explain operational changes during the interruption.
- Update processing-volume estimates if the business materially changed.
- Provide current website, menu, inventory, or sales-channel information where requested.
- Answer outstanding processor document requests.
- Ask the processor to confirm the status of any restrictions.
Ask for Specific Processing Restrictions to Be Reviewed
The merchant may need to request review of:
- funding holds;
- settlement restrictions;
- transaction limits;
- reserves;
- volume caps;
- account suspension; and
- compliance flags.
Do not treat regulatory reinstatement as an automatic cancellation of those measures. The provider can conduct a separate risk review under its contract.
Build a Compliance File That Doubles as an Underwriting Refresh Packet
A strong merchant account compliance file allows a retailer to answer an unexpected merchant account document request without reconstructing years of records.
| File Section | Keep Available | Why It Helps Underwriting |
| Licensing | Current/prior licenses, renewal receipts, filing confirmations, regulator correspondence, relevant inspections | Establishes status, timing, premises, and renewal history |
| Corporate | Entity registration, DBA records, EIN confirmation, ownership records | Confirms merchant identity and ownership |
| Location | Lease/property records, local business license, premises permits | Confirms approved operating location |
| Insurance | Applicable policies/certificates | Supports jurisdictional or contractual information requests where relevant |
| Payments | Merchant agreement, MID records, processor contacts, processing statements, previous underwriting requests | Allows fast analysis of notice, settlement, and underwriting issues |
| Calendar | Renewal opening dates, deadlines, expiration dates, insurance and permit dates, processor reminders | Prevents administrative lapses |
| Enforcement/reinstatement | Orders, appeal documents, actual stays, reinstatement orders | Documents exactly what changed and when |
Keep transaction records, receipts, customer-service evidence, and processor correspondence organized as well, because a documented chargeback and transaction-compliance process makes it easier to separate ordinary payment disputes from licensing or underwriting issues.
Build a License Renewal Compliance Calendar
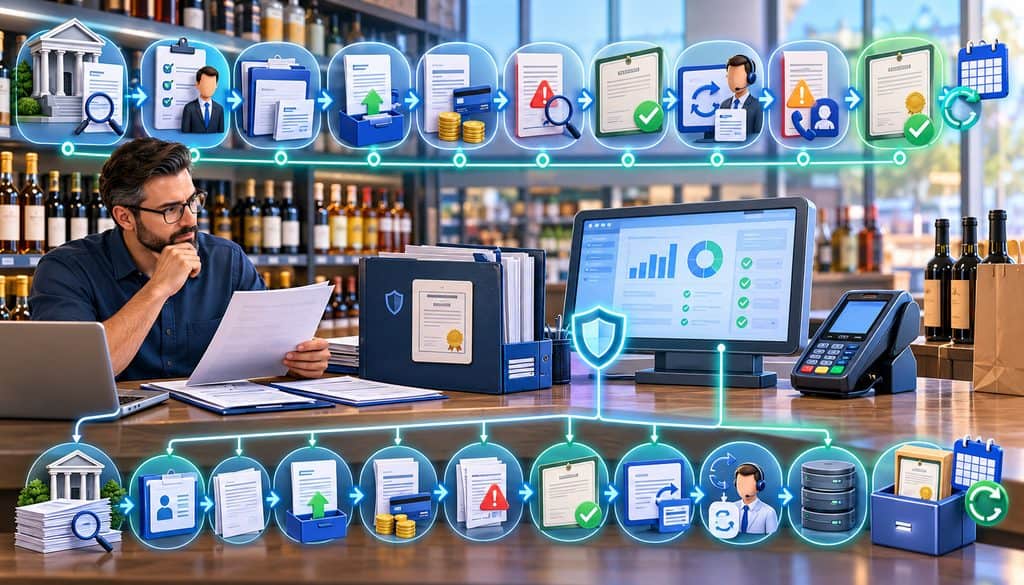
A license renewal compliance calendar should begin well before the statutory deadline, but the following intervals are an internal planning framework—not nationwide legal filing deadlines.
120–90 Days Before Expiration
- verify the regulator’s current instructions;
- confirm entity and ownership data;
- identify changed requirements;
- assign an internal owner; and
- inspect local-license dependencies.
90–60 Days
- file when the regulator permits;
- pay required charges;
- save submission confirmation; and
- calendar expected follow-up events.
60–30 Days
- resolve deficiencies;
- check official status;
- update the compliance file; and
- determine whether processor documentation needs refreshing.
30 Days Through Expiration
- escalate unresolved applications;
- establish whether authority continues if approval remains pending;
- notify processor where required; and
- prepare an operating plan based only on lawful activity.
After Renewal
- save the final license;
- verify effective and expiration dates;
- send it to the processor if required; and
- schedule the next cycle.
Merchant-Services Agents Should Treat License Renewal as Portfolio Risk
Agents serving liquor merchants can reduce avoidable disruption without attempting to practice liquor-license law.
Useful portfolio controls include recording expiration dates, sending renewal reminders, maintaining underwriting contacts, helping route documents, distinguishing an administrative renewal problem from a disciplinary event, and escalating material status changes.
Agents should not tell merchants that they are legally allowed to keep selling alcohol. That determination belongs with the applicable licensing authority and, where appropriate, qualified legal counsel.
What Processors Should Not Be Told
Avoid unsupported shorthand such as:
- “The license is basically active.”
- “The appeal means we can still sell.”
- “It was only technical.”
- “Nobody has actually shut us down.”
- “We changed the business category.”
Instead report the current official status, effective date, actual documented stay if one exists, permitted business activity, next regulatory milestone, and supporting documentation.
Accurate facts make the underwriting question easier to evaluate.
Illustrative Example — Renewal Filed but New License Has Not Arrived
Illustrative example: A package store files its renewal before expiration, but the replacement credential has not arrived.
The manager should:
- Check the regulator’s current rule for timely filed renewals.
- Determine whether legal authority continues after the displayed expiration date.
- Save the submission and payment confirmation.
- Check for processor document requests.
- Notify underwriting when contractually required.
- Provide official status evidence rather than a verbal explanation.
- Continue only transactions legally authorized.
- Send the final renewed license when issued.
The example deliberately does not assume that filing automatically extends operating authority.
Illustrative Example — License Suspended for a Defined Period
Illustrative example: A retailer receives an order suspending its alcohol-selling privileges for a defined period.
Alcohol activity follows the regulator’s order. Any lawful non-alcohol retail operation is analyzed separately under applicable law.
The merchant gives the processor the order and relevant dates, explains what lawful activity remains, and asks whether its existing MID may remain active for those transactions. The merchant preserves the response and sends reinstatement records before resuming normal alcohol-related processing.
The processor’s answer could depend on its contract and underwriting assessment; continued processing should not be assumed.
Frequently Asked Questions
Will my credit-card processor know if my liquor license expires?
It may. Verification can occur through merchant disclosures, public licensing records, scheduled document updates, compliance investigations, or underwriting reviews. Monitoring methods vary, so do not assume either constant automated monitoring or permanent invisibility.
Does an expired liquor license automatically terminate my merchant account?
No universal processor rule says that. The regulator determines alcohol-selling authority, while the processor separately acts under its merchant agreement and risk policy. A lapse can nevertheless trigger document requests, restrictions, re-underwriting, or termination.
Can I take card payments while my liquor license is suspended?
Do not process alcohol transactions the suspension makes unlawful. If other merchandise may legally be sold, ask whether the processor permits those transactions under the existing merchant account and approved business profile.
Can I still sell non-alcohol items during a liquor-license suspension?
Possibly, but it depends first on the suspension order and applicable law. The processor must separately decide whether the existing account remains suitable for that activity.
Does filing a liquor-license appeal let me continue selling alcohol?
Not necessarily. An appeal does not automatically mean a stay exists. Verify the governing state’s procedure and whether a stay or other continued authority has actually been issued.
What should I send my processor after reinstatement?
Typically, prepare the renewed or reinstated license, regulator order where applicable, effective date, evidence of satisfied conditions, current business and ownership information if changed, and responses to outstanding underwriting requests.
Can a processor hold funds because my liquor license expired?
A licensing problem can prompt a risk review, but any reserve, withholding, or settlement action should be evaluated under the applicable merchant agreement and facts. It should not be described as an automatic consequence of expiration.
How early should I prepare for liquor-license renewal?
An internal 90–120-day planning window is useful for gathering documents and checking current instructions, but it is not a statutory nationwide filing period. The actual filing window comes from the applicable regulator.
Build Your Liquor License Lapse Merchant Account Plan Before Renewal Season
A reliable liquor license lapse merchant account plan follows a simple sequence:
track renewal → file early → verify legal authority → preserve documentation → notify the processor when required → stop prohibited activity → continue only lawful and processor-approved sales → document reinstatement → request underwriting review
The state regulator determines what alcohol activity is lawful. The merchant agreement determines contractual card-acceptance obligations. The processor or acquirer determines account risk and underwriting status. The MCC describes payment activity but grants no alcohol-selling authority.
Keeping those four concepts separate is the best way to protect both compliance and legitimate payment continuity.